
10 Business Days to Close. 3 Weeks to Explain. Zero Time Left to Act.
Your variance report may be accurate. But if it arrives after the decision window, what value is it really creating?
Your Variance Report Is Telling You What Happened. But Is It Telling You in Time? The problem isn’t variance analysis. It’s the time between the variance occurring, Finance understanding why it happened, and the business acting on it. Not late by the calendar—late by the time it takes to matter. By the time the variance report reaches the CFO’s desk, the decision it was meant to inform may already have been made. That’s not a data problem. It’s a design flaw. And it’s fixable.
There’s a particular dread that settles over a business review when the variance slide comes up.
Not because the numbers are bad. Often they’re fine. It’s that nobody in the room fully trusts them yet.
Is that COGS spike a pricing issue or a units issue? Is the marketing overspend a timing shift or a real miss? The honest answer, more often than anyone wants to admit, is: we’ll get back to you.
And by the time anyone does, the moment to act on it has usually passed.
That’s the quiet failure mode of variance analysis in most organizations. It was built to be a diagnostic tool — a way of catching problems while they’re still small and cheap to fix.
In practice, it’s become a compliance ritual: produce the number, defend the number, move on. The information is technically there. The insight rarely is.
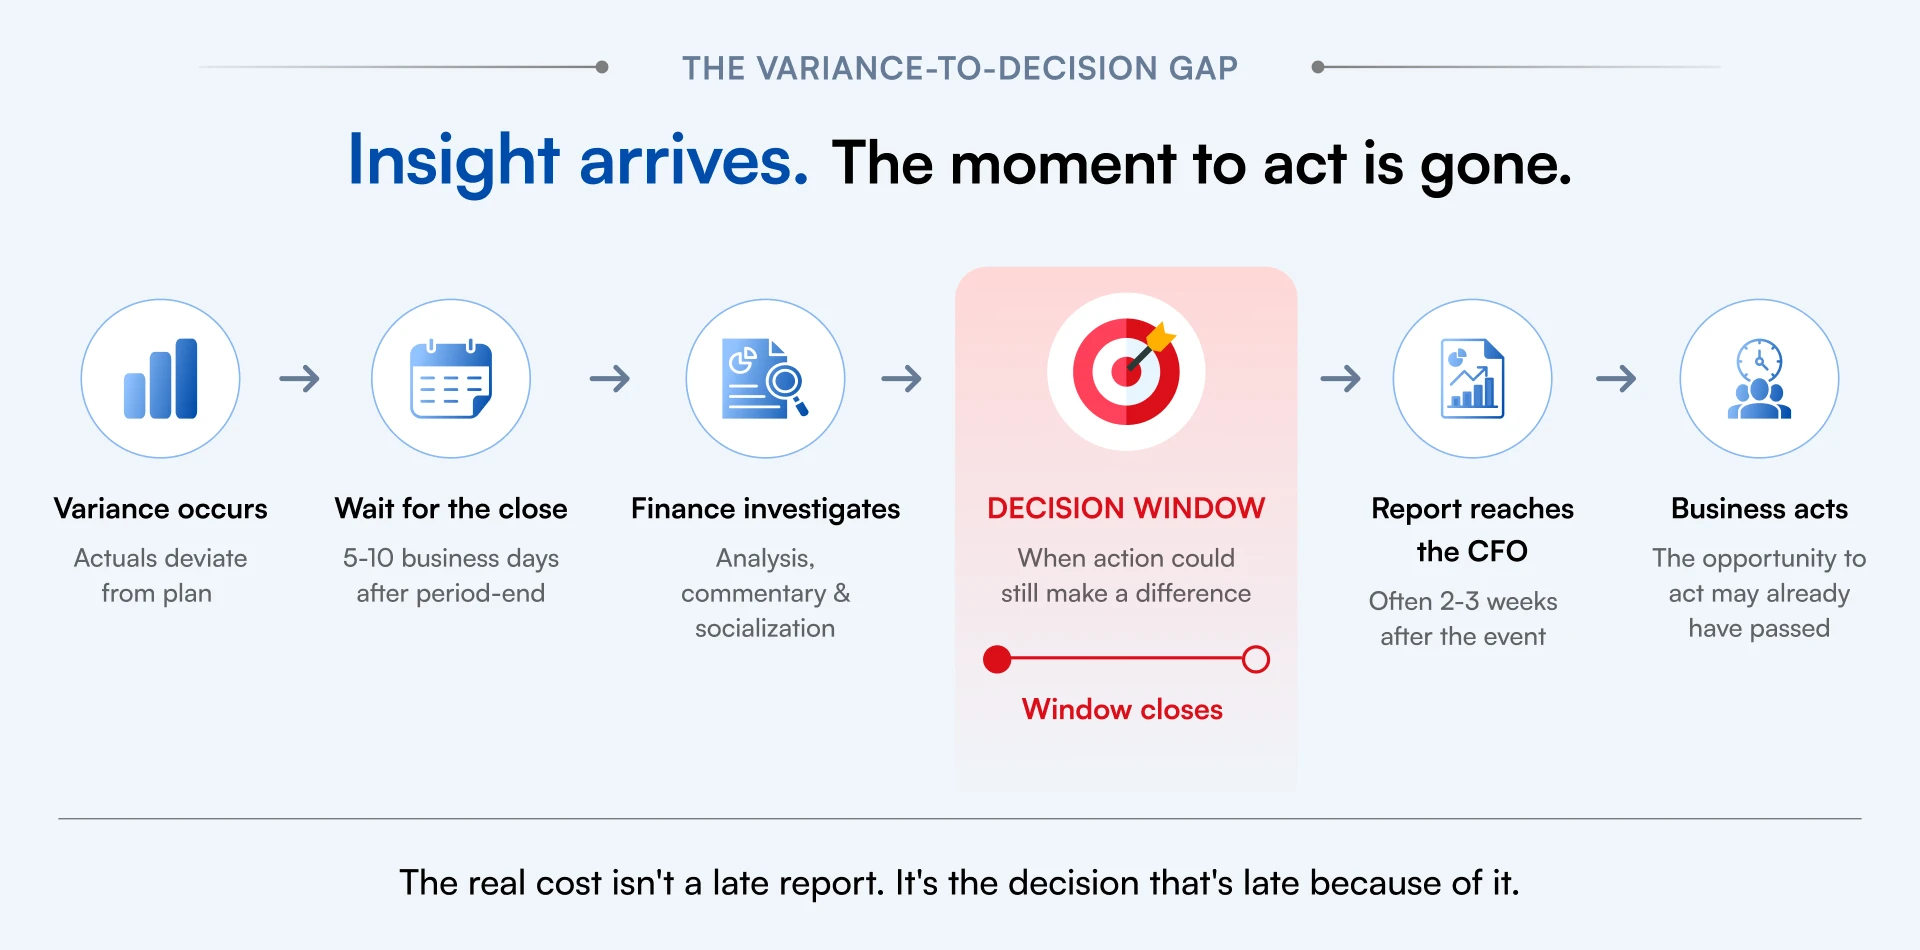
The real cost of slow variance analysis isn’t the report that’s late — it’s the decision that’s late because of it.
Why the Process Breaks Down
It’s rarely one dramatic failure. It’s a thousand small frictions, compounding.
Start with where the data lives. Actuals sit in the ERP. Budget sits in a planning tool. The context that explains a variance — a delayed shipment, a renegotiated contract, a one-time headcount shift — sits in someone’s inbox, or their memory.
Pulling it together is still, for most teams, a manual act of archaeology performed fresh every month.
Then there’s timing. Variance analysis waits for the close — five, eight, sometimes ten business days after period-end. Add time to build commentary and socialize it, and the conversation often lands two to three weeks after the event it describes.
The business has already moved on. Finance is narrating history.
Even when data and timing cooperate, there’s a harder problem: variance tells you what happened, not why.
“Revenue missed by 8%” is not an insight — it’s a prompt for one. Price? Volume? Mix? A single lost customer? Without that breakdown, every conversation starts from zero.
And when real signal does surface, it’s often buried in noise. Systems that flag every deviation – material or not – train people to stop reading.
For Example:
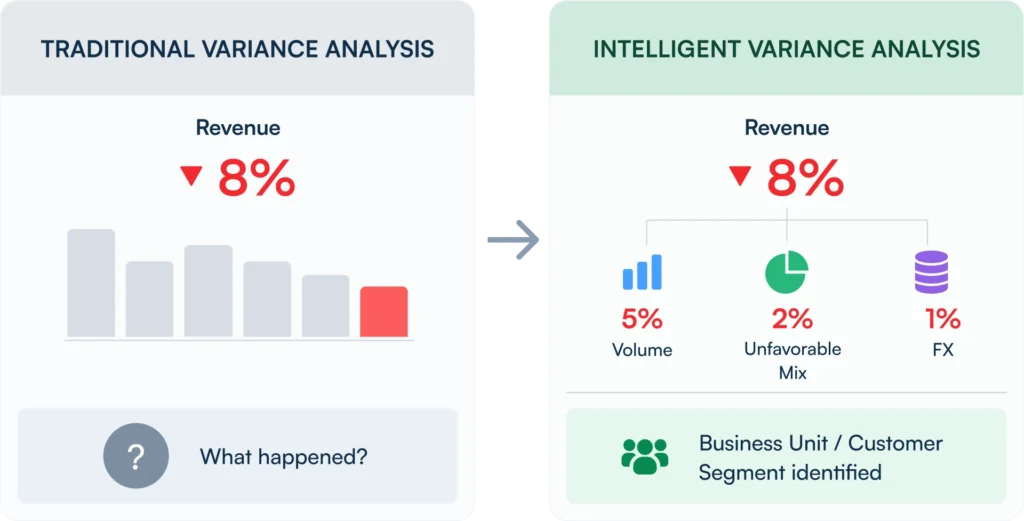
The conversation changes from “Why did revenue decline?” to “What are we doing about it?”
A CFO who gets forty variance alerts a month and acts on two has built a system that cries wolf thirty-eight times out of forty.
Then there’s the cost nobody puts on a slide: talent. The sharpest analysts in the building spend most of their week pulling and formatting data, not interpreting it.
That’s not a data problem. It’s an allocation problem – your best minds doing your most replaceable work.
This is where AI changes the equation.
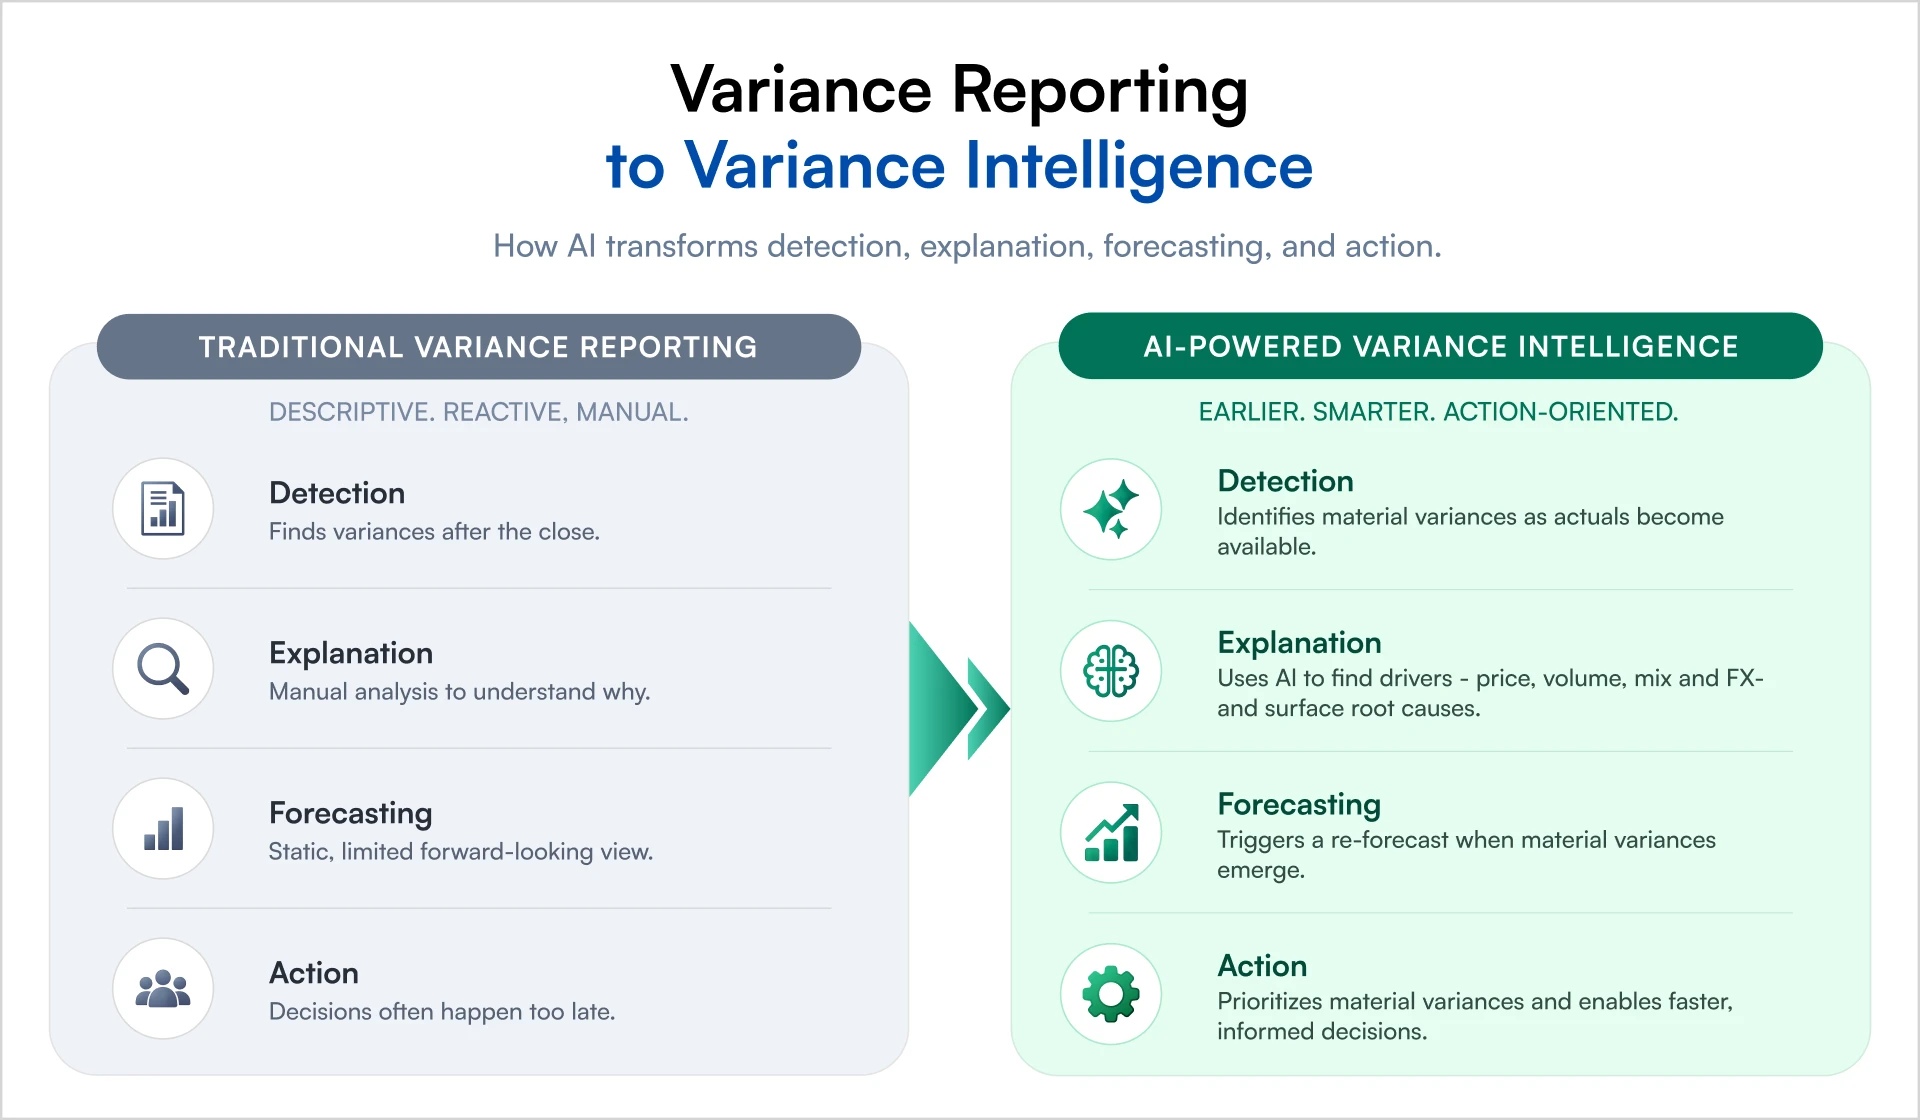
Instead of simply automating the mechanics of variance reporting, AI-powered variance analysis can turn variance analysis from a reporting exercise into an intelligent investigation workflow, detecting meaningful anomalies, identifying root causes, drafting commentary, and directing Finance’s attention to the variances that matter most.
What Automation Actually Changes – and What It’s Worth to You
“Automate variance analysis” is a vague instruction until it’s tied to a concrete capability and a concrete payoff. Here’s the direct line from each:
Earlier variance detection, not month-end surprises
Instead of waiting for the close, the system watches actuals as they land and flags material deviations as soon as the underlying data becomes available.
What it’s worth to you: you find out about a margin slip while it’s still a rounding error — not after it’s shown up in the quarterly numbers you must explain to the board.
Automatic root-cause decomposition
Material variances can be automatically decomposed into price, volume, mix, and FX effects, for every business unit, without an analyst opening a single spreadsheet.
What it’s worth to you: you walk into a leadership meeting already knowing whether a miss is a pricing problem or a demand problem — so the conversation starts at the decision, not at the detective work.
AI-drafted commentary
The system writes the first version of management commentary directly from the numbers — in plain, board-ready language — for your analysts to refine.
What it’s worth to you: consistent, defensible narrative across every business unit and every reporting cycle, with far less time spent wordsmithing and far more spent validating.
Noise suppression through materiality
Statistical thresholds separate genuine outliers from routine month-to-month noise, so alerts land only when they’re worth your attention.
What it’s worth to you: your inbox — and your team’s judgment — stop being trained to ignore the system.
Capacity reallocation
Automating the mechanical work — pulling, cleaning, reconciling, formatting — can free meaningful analyst capacity for scenario modeling, business partnering, and decision support.
What it’s worth to you: the same headcount now covers scenario modeling, deal support, and board prep — without a single new hire.
Forecast-linked variance
Every material variance automatically triggers a re-forecast recommendation, instead of sitting as an isolated data point.
What it’s worth to you: your forecast stays live and credible year-round, instead of going stale the moment actuals start drifting from plan.
Automation doesn’t replace the CFO’s judgment. It clears everything else off the desk so that judgment gets used on the things that need it.
Recommendations: Where to Start
You don’t need to automate everything at once. You need to sequence it so each step earns the next.
- Audit your data plumbing before you buy anything. Map where actuals, budget, and operational context live today. Most automation projects stall not because the software is wrong, but because the underlying data was never unified.
- Pilot on one business unit, not the whole company. Pick the unit with the messiest variance history. Prove the model there, tune the thresholds, then scale – don’t try to boil the ocean in month one.
- Set materiality thresholds before you go live. Decide, in writing, what counts as a footnote, a memo, and a same-day call – before the system starts generating alerts, not after your team starts ignoring them.
- Pair variance automation with a rolling forecast. A fast variance engine sitting on top of a static annual budget only gets you half the value. Make the forecast update as the variance data does.
- Redeploy the hours you free up – deliberately. Decide in advance where reclaimed analyst time goes – scenario planning, business partnering, M&A support – or it will quietly get absorbed back into more manual reporting.
- Keep a human on every material variance. Automate the detection and the first-draft narrative. Keep judgment, escalation calls, and board framing with your team – automation earns trust by being fast and transparent, not by being invisible.
- Review the thresholds quarterly. What counts as material changes as the business grows, margins shift, or a new segment scales. A materiality rule set once and never revisited becomes noise again within a year.
The Real Measure of a Modern FP&A Function
Every finance team can explain what happened last month. Fewer can explain it fast enough, precisely enough, and consistently enough for the explanation to still matter.
That gap — between reporting the past and shaping what’s next — is exactly where automation earns its keep.
The CFOs who close that gap aren’t doing less variance analysis. They’re doing it faster, with sharper root causes, and with their best analysts spending time on judgment instead of formatting.
The ones who don’t will keep having the same meeting: everybody nods, nobody’s quite sure why the number moved, and the real decision gets made three weeks too late to matter.
The question worth bringing to your next leadership meeting isn’t “what happened?” It’s “how fast did we know — and how fast did we move?”
About the Author
Ramesh Tavva is the CFO and leads the Finance & Accounting practice at CES. With more than 25 years of experience across Finance & Accounting, financial operations, audit, taxation, technology, and business transformation, he helps CFOs and finance leaders modernize finance functions to drive efficiency, agility, and business value. His expertise spans finance transformation, intelligent automation, treasury management, accounts payable automation, cash reconciliation, fund accounting, variance analysis, and financial decision support. Ramesh leverages analytics, Generative AI, and Agentic AI to help organizations build scalable, data-driven, and future-ready finance operations.